If you’re buying a home in Wilmington with a conventional mortgage this fall, the appraisal on your purchase probably looks different than the one your neighbor got last year. On Monday, November 2, 2026, Fannie Mae and Freddie Mac’s new appraisal reporting standard, known as UAD 3.6, became the required format for new appraisal reports submitted to the two mortgage companies. It’s a behind-the-scenes change that touches most financed sales in New Hanover County. Here’s what changed, what didn’t, and how to use it.
What Changed on November 2
For years, appraisers worked from a set of fixed forms: one for a typical single-family home, another for condos, others for exterior-only or desktop appraisals. According to Fannie Mae’s Uniform Appraisal Dataset page, the two companies have worked on this redesign since 2018 to replace those forms with “a single data-driven, flexible, and dynamic appraisal report for any residential property type,” called the Uniform Residential Appraisal Report, or URAR.
As MarketReview reported on November 2, 2026, the deadline is tied to when a report is first submitted to the agencies’ portal, not when the appraiser visited the house. So an appraisal done in late October but submitted this week generally has to use the new format.
Some lenders get extra time
Not every lender switched overnight. In Lender Letter LL-2026-08, published September 30, 2026, Fannie Mae announced a temporary exception for lenders that couldn’t implement UAD 3.6 by November 2. Lenders that request it can keep submitting the older UAD 2.6 reports through May 19, 2027, while they finish the transition. If you’re under contract now, your appraisal could be in either format, depending on your lender.
What’s New in the Report, and Why It Matters on the Coast
For coastal buyers and sellers, the most interesting changes are two brand-new sections. In its Q4 2025 Appraiser Update, Fannie Mae explained that the URAR now includes a Disaster Mitigation section and an Energy Efficient and Green Features section.
Disaster mitigation features get their own space
Fannie Mae says the Disaster Mitigation section uses 12 standardized features, including fortified roofs, impact-resistant glass or shingles, fire-resistant decking, and storm shelters, plus an “Other” option the appraiser can describe. In a market where hurricane season shapes insurance costs, that’s meaningful: these features now have a defined place in the report.
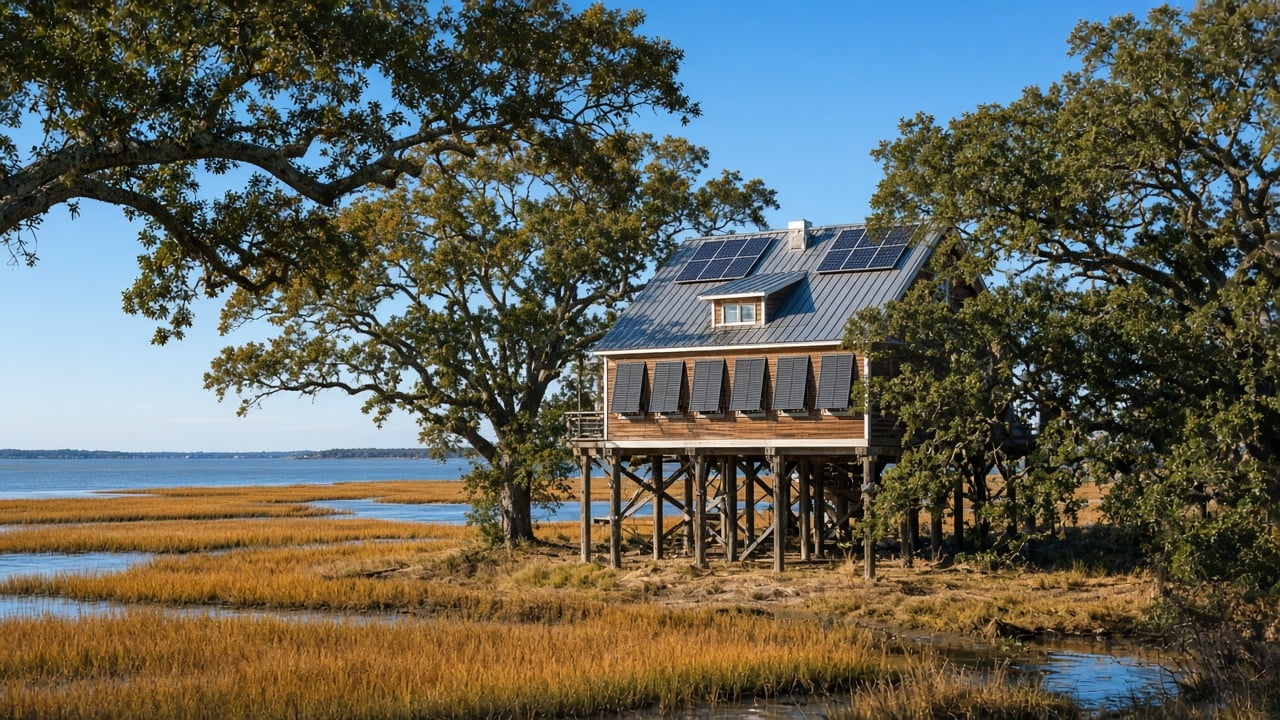
If you own a home in Ogden, Porters Neck, Monkey Junction, or out on Wrightsville or Carolina Beach and you’ve invested in a FORTIFIED roof, impact windows, or similar upgrades, you’ll want appraisers to see them. (We covered the state grant and insurance side of this in our guide to FORTIFIED roofs on the Cape Fear coast.) A line in the appraisal doesn’t automatically mean a higher value. The appraiser still has to support any adjustment with market evidence. But it does mean the feature is recorded consistently.
Energy and green features
The energy section has three parts: renewable energy components (like solar), building certifications, and green efficiency ratings. Fannie Mae notes that the appraiser is asked to rate whether each feature has a beneficial, neutral, or adverse effect on value and marketability.
Tighter definitions for “new” and “remodeled”
Fannie Mae also tightened its condition ratings. A C1 rating, the top condition rating, now carries a 12-month age limit for new construction, and C2 is defined as new construction or a home remodeled “to the studs” within 36 months with no deferred maintenance. That’s relevant here, where so many buyers compare a brand-new build in a growing subdivision against a renovated resale closer to town.
What Hasn’t Changed
The new format doesn’t change mortgage rates or loan limits, and it doesn’t mean every loan now needs a traditional appraisal. Appraisers still value a home based on comparable sales and local market conditions. In the Wilmington area, that means things like flood zone, proximity to the water, HOA amenities, and neighborhood still drive the numbers. (If flood zones are on your mind, start with our Wilmington-area flood zone guide.)
This standard applies to appraisals delivered to Fannie Mae and Freddie Mac, which covers most conventional loans. If you’re using an FHA, VA, or USDA loan, or a jumbo or portfolio loan, ask your lender which report format and requirements apply to you.
Practical Tips for Buyers and Sellers
If you’re buying
- Ask your lender which format they’re using.
- Read the appraisal carefully. The new report is organized differently, so check that the property details, condition rating, and any mitigation or energy features match what you saw on your showings and in your home inspection.
- Keep your timeline in mind. In North Carolina, the appraisal often lands during or near the due diligence period. Build in a little cushion as lenders and appraisers settle into the new system.
If you’re selling
- Gather your documentation now. A dated upgrade list plus FORTIFIED certificates, impact window or shutter specs, solar ownership papers, energy certifications, and permits for major remodels make it easier for an appraiser to identify and describe your home’s features.
- Be realistic about value. Upgrades help a home stand out, but appraisers still need local sales data to support adjustments. Pricing based on recent comparable sales remains the best protection against an appraisal gap.
Frequently Asked Questions
Does the new appraisal format change my home’s value?
Not by itself. UAD 3.6 changes how appraisal information is reported and organized. Value still comes from the appraiser’s analysis of the property and comparable sales.
My appraisal was done before November 2. Do I need a new one?
Not necessarily. Your lender handles the submission, and some lenders have an exception that allows the older format through May 19, 2027. Ask your loan officer if anything changes for your file.
Will my hurricane upgrades show up in the appraisal?
The new report has a dedicated Disaster Mitigation section that includes features like fortified roofs and impact-resistant glass. Whether a feature affects the value depends on what local market data supports.
Talk It Through With a Local Team
Whether you’re buying in Wilmington, selling at the beach, or weighing a move to the Cape Fear coast, we’re glad to walk you through it. Contact Aspyre Collective to talk with our team about your next move.