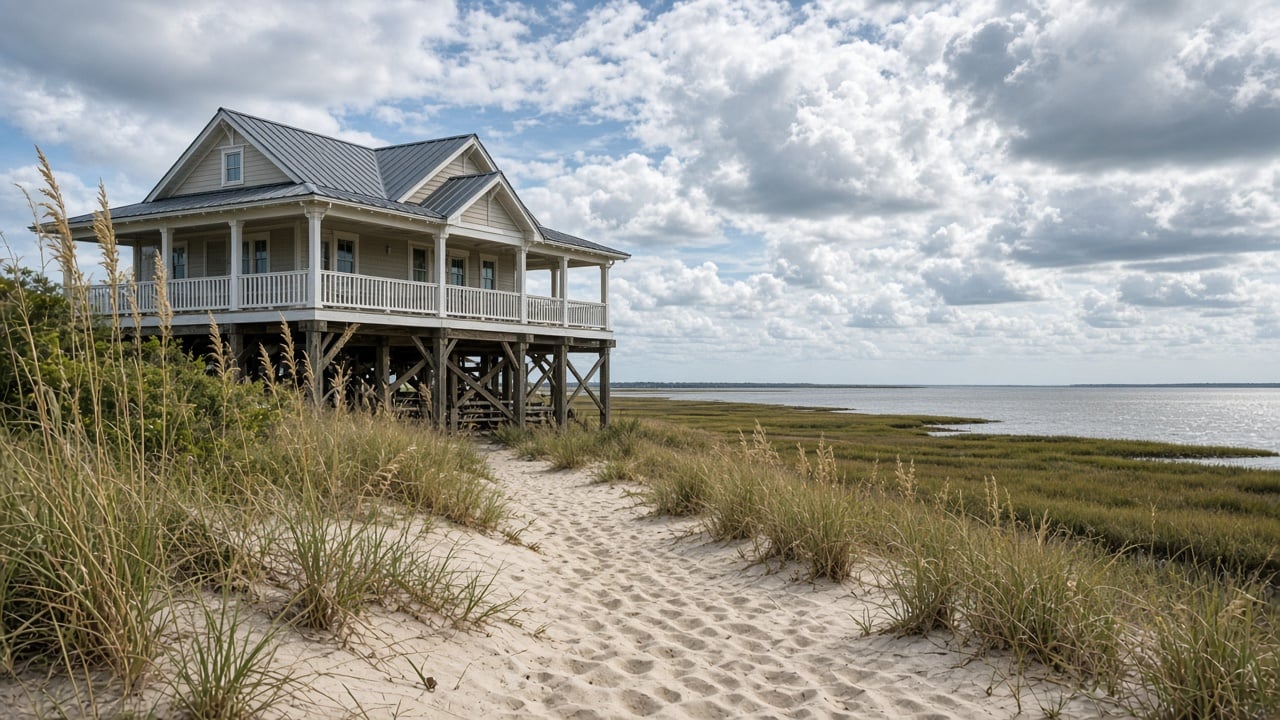
Two Pender County homes with the same price, size, and age can come with very different homeowners insurance quotes. A cottage on Topsail Island, a newer home in Hampstead, and a farmhouse outside Burgaw all sit in the same county, but North Carolina prices them in different rating territories. If you’re buying anywhere in Pender, understanding how that works will help you budget accurately and avoid surprises during due diligence.
How North Carolina Sets Homeowners Rates
In North Carolina, the N.C. Rate Bureau, which represents insurance companies, files proposed homeowners rates with the N.C. Department of Insurance. The state groups the map into rating territories, and rate changes are approved territory by territory. Individual companies can deviate from those rates with approval, and your final premium still depends on the home itself: roof age, construction, coverage amount, deductibles, claims history, and credits.
The Two-Year Settlement
In January 2025, the Department of Insurance announced a settlement of the Rate Bureau’s 2024 request, which had sought an average 42.2% statewide increase and up to 99.4% in some areas. The settlement instead set an average statewide base rate increase of 7.5% on June 1, 2025, and another 7.5% on June 1, 2026. The second step is now in effect for new and renewal policies. The agreement also bars the Rate Bureau from seeking another increase before June 1, 2027.
Pender County’s Three Territories
Statewide averages don’t tell the whole story here. According to the Department of Insurance’s territory table, Pender County falls into three different territories, and coastal areas saw larger approved increases:
- Territory 120, beach areas of Brunswick, Carteret, New Hanover, Onslow, and Pender counties: approved increases of 16% in 2025 and 15.9% in 2026. In Pender, this generally means Topsail Island.
- Territory 140, eastern coastal areas: 10.5% in 2025 and 10.1% in 2026. The listed ZIP codes include 28443 (Hampstead) and several Wilmington ZIPs.
- Territory 160, western coastal areas: 5% in 2025 and 4.8% in 2026. The listed ZIP codes include 28425 (Burgaw) and 28457 (Rocky Point), along with other inland Pender ZIPs.
Those percentages describe changes to base rates, not total premiums, and they don’t mean an inland home is cheap to insure. But they show why where a home sits in Pender can matter as much as the home itself. Before you write an offer, check the property’s ZIP code against the state table, and remember that island properties are rated as beach areas.
The Coastal Property Insurance Pool
When buyers near the coast can’t find coverage in the regular market, many turn to the North Carolina Insurance Underwriting Association, also called the Coastal Property Insurance Pool and long known locally as the Beach Plan. Under state law (G.S. 58-45-5), the pool serves beach and coastal areas in 18 coastal counties, including Pender. The beach area is generally the land south and east of the Intracoastal Waterway, which in Pender means Topsail Island. The rest of the county is considered coastal area.
Many island homes carry a wind policy through the pool and a separate policy for other perils. Ask your agent early how the home you’re considering would be insured.
Flood Insurance Is a Separate Policy
Standard homeowners policies don’t cover flood. That matters across Pender, not just on the island, since low-lying areas near rivers, creeks, and the sound can flood too. If a home is in a FEMA special flood hazard area and you’re using a federally backed mortgage, your lender will require flood insurance. Even outside those zones, it’s worth getting a quote. See our posts on flood zones and the Dec. 11 flood insurance deadline. Topsail Beach owners should also read about the town’s flood ordinance and insurance discount.
Ways to Keep Premiums in Check
- Get quotes during due diligence. Don’t wait until a week before closing. In NC, the due diligence period is your chance to walk away if insurance costs don’t work.
- Ask about roof age and wind mitigation. Wind mitigation features and a newer roof can earn credits. A FORTIFIED roof can earn larger discounts, as we explained in our post on FORTIFIED roofs.
- Compare deductibles. Coastal policies often carry a separate wind or hurricane deductible, sometimes a percentage of the dwelling coverage. Know the dollar amount, not just the percentage.
- Ask about the seller’s current policy. Knowing what the current owner pays, and with whom, gives you a starting point.
- Watch the calendar. When a named storm threatens the coast, insurers commonly stop writing new policies in the area until it passes. Hurricane season runs through Nov. 30, so build in time.
Frequently Asked Questions
Why are insurance quotes higher on Topsail Island than in Burgaw?
Topsail Island is in the beach-area territory, which carries more wind risk and saw a larger approved increase (15.9% in 2026) than Pender’s western coastal territory (4.8%).
Which territory is Hampstead in?
The state’s table lists ZIP code 28443, which covers Hampstead, in Territory 140, the eastern coastal area.
Will rates go up again next year?
Under the settlement, the Rate Bureau can’t seek another homeowners increase before June 1, 2027. Individual insurers can still change their own pricing within the rules.
Can I get insurance through the Coastal Property Insurance Pool anywhere in Pender?
Pender is one of the 18 counties the pool serves under state law, covering both beach and coastal areas. Eligibility and coverage depend on the property, so ask an agent.
Buying in Pender County?
Insurance is one of the biggest variables in a coastal purchase, and we help buyers line up quotes early so there are no surprises. Contact Aspyre Collective to talk through homes in Hampstead, Topsail Island, Burgaw, Rocky Point, and beyond.