If you own a home anywhere from Topsail to Sunset Beach, your roof does more work than almost any other part of the house. It’s your first line of defense in a hurricane, and in our market it also has a real effect on what you pay for insurance. That’s why more Cape Fear homeowners, buyers, and sellers are asking about FORTIFIED roofs. Here’s a plain-English look at what they are, the state-backed grants that help pay for them, and how they can matter when you buy or sell in Brunswick, New Hanover, and Pender counties.
What Is a FORTIFIED Roof?
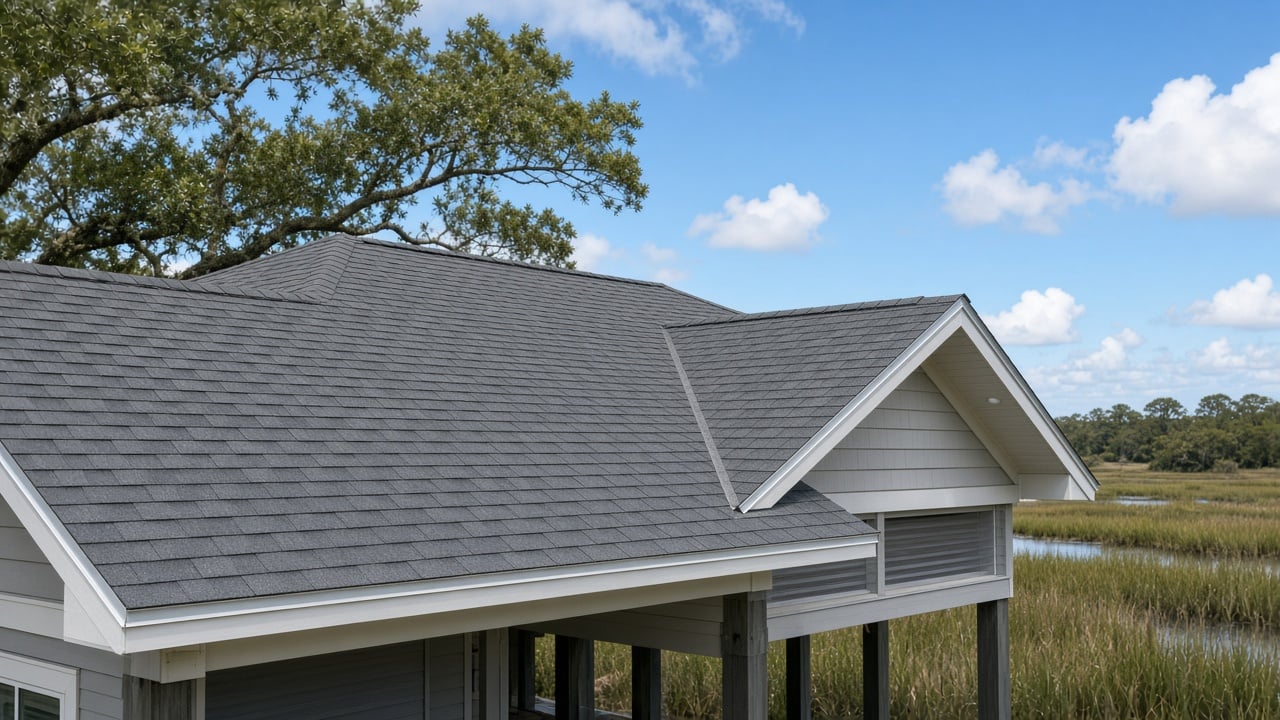
FORTIFIED is a voluntary construction and re-roofing standard created by the Insurance Institute for Business & Home Safety (IBHS), a nonprofit research group. According to the North Carolina Department of Insurance, the standard goes beyond what most building codes require, and every job is inspected and verified to confirm it was done correctly.
In practice, a FORTIFIED roof includes upgrades like stronger roof deck attachment, a sealed roof deck to keep out wind-driven rain, and locked-down edges. When the work passes a third-party evaluation, IBHS issues a designation certificate that lasts five years and can be renewed.
Does it actually make a difference?
When the state announced its 2025 coastal roof grant program at a FORTIFIED home in Sunset Beach, Insurance Commissioner Mike Causey cited research from N.C. State University’s Institute for Advanced Analytics. That research found that homes with a FORTIFIED roof had about 35 percent fewer claims after Hurricanes Matthew, Florence, Dorian, and Isaias, and that when claims were filed, the damage was about 23 percent less severe (NC DOI, July 17, 2025).
The Two Roof Grant Programs That Cover Our Area
The North Carolina Insurance Underwriting Association (NCIUA), also known as the Coastal Property Insurance Pool, runs two grant programs. Which one applies depends on where the home sits.
Strengthen Your Coastal Roof (mainland coastal areas)
The Strengthen Your Coastal Roof program offers grants of up to $6,000 toward a FORTIFIED roof. It covers the coastal area of 18 counties, including Brunswick, New Hanover, and Pender, but not the beach areas, which have their own program. Think Leland, Ogden, Monkey Junction, Hampstead, Burgaw, Shallotte, and similar mainland communities.
Strengthen Your Roof (beach and barrier island areas)
For homes east of the Intracoastal Waterway and on the barrier islands, the Strengthen Your Roof program offers grants of up to $10,000. That’s the one to look at for places like Wrightsville Beach, Carolina Beach, Kure Beach, Topsail Island, Oak Island, Holden Beach, Ocean Isle, and Sunset Beach.
Who qualifies and how it works
- You need an NCIUA policy. The grants are for active NCIUA homeowners or wind-and-hail policies with building coverage. FAIR Plan full-peril dwelling policies aren’t eligible.
- It’s first come, first served. Funding is limited, so check the program site for current availability before you plan around it.
- Photos come first. The application asks for at least four exterior photos, one of each side of the home.
- You get 18 months. Once NCIUA and IBHS approve the application, you have 18 months to finish the roof and earn the designation.
- Use a certified contractor. Since November 1, 2025, the coastal program only allows IBHS-certified FORTIFIED roofing contractors, and the program site keeps a directory of participating contractors.
NCIUA also offers a no-cost Stronger Roof Endorsement to all of its policyholders. Per the NC DOI, it adds up to $5,000 in coverage for FORTIFIED upgrades when a roof is replaced because of a covered claim.
The Insurance Savings
A FORTIFIED designation can earn a mitigation credit on the wind portion of your coverage. NCIUA’s 2026 credit schedule for frame homes (effective June 1, 2026) shows a FORTIFIED Roof credit on a new roof of roughly 3.7 to 6.4 percent on homeowners policies and 5.6 to 7.9 percent on wind-only policies, depending on the rating territory. Higher FORTIFIED Silver and Gold designations, which add more upgrades beyond the roof, earn larger credits.
If you’re insured through a private company instead, the NC DOI’s advice is simple: ask your agent or insurer what credits they offer. And if you own a rental, the state’s 2026 dwelling rate settlement also included mitigation credits for fortified homes and roofs. We covered that settlement in our post on new NC dwelling insurance rates for rental owners.
What It Means If You’re Buying
When you’re touring homes near the coast, it’s worth asking a few roof questions early:
- How old is the roof, and is there a FORTIFIED certificate? If so, when does it expire?
- Does the home have a hip roof or opening protection like impact windows or shutters? Those features can earn credits too.
- What does the current owner pay for wind coverage, and who’s the carrier?
Get insurance quotes during your due diligence period, not after. Roof age and type can change a quote a lot in our market, and a designated roof may make a home cheaper to own month to month. Pair this with a look at the flood zone, too. Our Wilmington-area flood zone guide walks through that side of the picture.
What It Means If You’re Selling
If your roof is near the end of its life, replacing it to the FORTIFIED standard may be worth pricing out before you list, especially if you carry an NCIUA policy and could qualify for a grant. Keep in mind the approval and contractor timeline, so start early. If you already have a designation, put the certificate in your listing paperwork. Buyers here know insurance is a big part of the monthly cost, and proof of a stronger roof is an easy point to highlight.
FAQ
Can I get a grant if I’m insured by a private company?
The NCIUA grant programs are for NCIUA policyholders. Private insurers set their own mitigation credits, so ask your agent what’s available.
Is a FORTIFIED roof the same as a new roof?
No. It’s a new roof installed to a specific IBHS standard and verified by a third-party evaluator. A regular replacement doesn’t earn the designation.
Talk It Through With a Local Team
Insurance and roof condition are now a big part of every coastal home decision, whether you’re buying in Hampstead, selling on Oak Island, or weighing a move to Leland. If you’d like help sorting out what a roof upgrade could mean for your purchase or sale, we’re glad to help. Contact Aspyre Collective and let’s talk about your plans.